


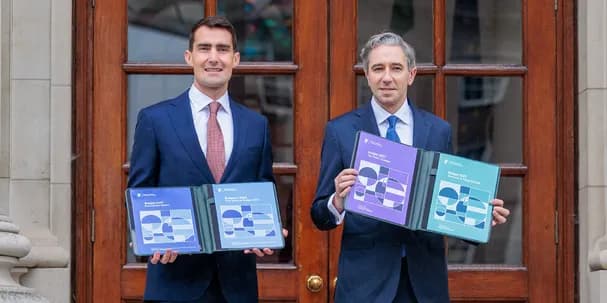
Ireland is tightening its tax policy on tobacco and vaping products, with higher cigarette duties already in effect and a further increase in e-liquid taxation scheduled for the start of 2027.
Under the government’s Budget 2027 measures, the tax burden on a pack of 20 cigarettes in the most popular price category has increased by €1, including VAT, from October 7, 2026. Meanwhile, Ireland plans to raise its E-liquid Products Tax (EPT) from €0.50 to €0.70 per millilitre on January 1, 2027, representing a 40% increase in the rate of the tax.
The changes affect different parts of the nicotine and vaping market. Cigarette and other tobacco duties have already increased, while the higher e-liquid rate is a future measure that manufacturers, importers, distributors, and retailers will need to prepare for.
Cigarette Tax Rises by €1 per Pack
The latest tobacco duty increase took effect on October 7, 2026. For a pack of 20 cigarettes in Ireland’s most popular price category, the government estimates a €1 increase in the tax-inclusive retail price if the full amount is passed on to consumers.
The measure also includes proportional increases for other tobacco products, including cigars, rolling tobacco, and other smoking tobacco. The precise retail impact will depend on the product and how businesses adjust their prices.
According to the Irish parliamentary financial resolution, the government expects the additional tobacco duties to generate approximately €63.1 million in a full year, with a further €5.1 million expected during the remainder of 2026. Officials have presented higher tobacco taxation as part of Ireland’s broader effort to discourage smoking and reduce uptake among younger people.
For consumers, the immediate consequence is a higher tax burden on cigarettes and other tobacco products. For retailers, the change means updating prices and accounting for the revised duty rates.
E-Liquid Tax to Increase from €0.50 to €0.70 per Millilitre
The more significant upcoming change for the vaping sector is the planned increase in E-liquid Products Tax.
For more context on how changing regulations affect the vaping industry, read our guide to vape taxes and regulations in the UK and Europe.
Ireland introduced EPT on November 1, 2025, at a rate of €500 per litre, equivalent to €0.50 per millilitre. Under the Budget 2027 announcement, the rate is due to increase by €0.20 per millilitre to €0.70 per millilitre from January 1, 2027.
That represents a 40% rise in the tax rate. The increase applies to e-liquids used in vaping products, whether or not the liquid contains nicotine. The tax is calculated by volume rather than by nicotine strength.
The following examples show the difference between the current rate and the announced rate:
| E-liquid volume | Current tax at €0.50/ml | Planned tax at €0.70/ml |
|---|---|---|
| 2ml | €1.00 | €1.40 |
| 5ml | €2.50 | €3.50 |
| 10ml | €5.00 | €7.00 |
These figures represent EPT alone, before VAT and other pricing considerations. They should not be interpreted as guaranteed increases in the final shop price of a vape or bottle of e-liquid. The eventual retail impact will depend on how manufacturers, importers, and sellers respond to the higher tax.
Both Nicotine and Nicotine-Free E-Liquids Are Covered
Ireland’s e-liquid tax is based on the product’s volume, not simply on whether it contains nicotine.
The Irish Revenue guidance states that EPT applies to both nicotine-containing and nicotine-free e-liquids used in e-liquid inhalation products. Certain products used exclusively as licensed nicotine-replacement medicines are treated differently under the applicable rules.
This broad scope is important for businesses selling a variety of vaping liquids. A product’s nicotine concentration alone does not determine whether EPT applies, so suppliers need to assess the product category and the relevant tax requirements.
Official guidance also explains that EPT generally becomes payable when a taxable e-liquid product is first supplied in Ireland. Producers and importers making that first supply are typically responsible for registering, accounting for the tax, and meeting the relevant filing obligations. Businesses further down the supply chain should confirm their own responsibilities under the rules.
What the Higher Vape Tax Could Mean for Retail Prices
The increase from €0.50 to €0.70 per millilitre adds €2 in EPT to a 10ml bottle of e-liquid, before VAT. For products sold in different sizes, the additional tax scales with the amount of liquid.
Tax changes are only one factor affecting the final price of vaping products, so readers can also explore our guide to why vape prices are increasing for a broader look at the costs facing the industry.
However, the tax increase does not automatically mean every product’s shelf price will rise by exactly the same amount. Businesses may absorb part of the additional cost, pass it on to customers, or adjust prices in other ways.
Vape retailers and distributors will need to review product pricing, stock planning, and supplier arrangements before the new rate takes effect. Importers and first-supply businesses should also check the latest Revenue guidance to ensure that their registration, records, and tax calculations remain compliant.
For consumers, the practical effect will become clearer as retailers publish prices closer to the implementation date.
A Rapid Change Following the Introduction of EPT in 2025
Ireland’s e-liquid tax was introduced under the Finance Act 2024 and came into effect on November 1, 2025. The planned increase announced in Budget 2027 would therefore raise the rate roughly 14 months after the tax first took effect.
Before the Budget announcement, the government had reported more than €22 million in provisional revenue from EPT since its introduction. The new rate continues Ireland’s move toward a higher tax burden on vaping liquids alongside successive increases in tobacco duties.
The two measures operate on different schedules: the latest tobacco duty rates took effect on October 7, 2026, while the announced higher EPT rate is scheduled for January 1, 2027. Businesses should distinguish between the rules already in force and the upcoming change when planning prices and compliance.
What Businesses and Consumers Should Watch Next
The key date for Ireland’s vaping market is January 1, 2027. Before then, suppliers and retailers should review the final applicable tax requirements, confirm how the new rate affects their products, and prepare for any necessary price changes.
Consumers should compare final retail prices rather than assume the tax increase will be passed on uniformly. Because EPT is volume-based, the additional tax differs according to the amount of liquid in a product.
Ireland’s latest Budget measures increase taxes on both combustible tobacco and e-liquids. The cigarette duty increase is already in effect, while the planned 40% rise in e-liquid tax will add another cost consideration for Ireland’s vaping industry at the start of 2027.